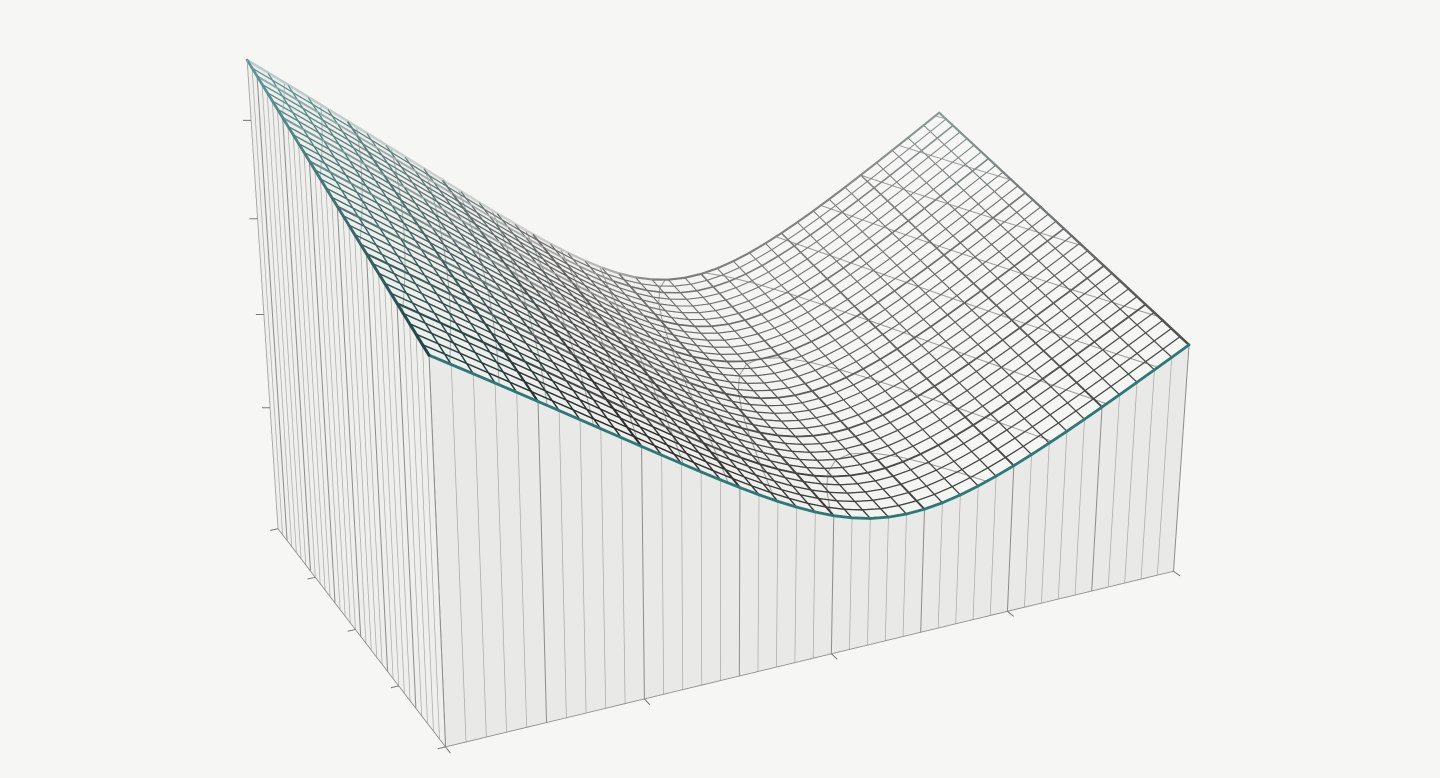
SABR volatility surfaceρ = −0.35
Illustrative. Constructed inputs, not market quotes and not any bank's data. Drawn by the Lab's SABR function, 1 to 5 years.
Chih ChenALM modeling education
Models are math.
Risk is human.
This site is about how bank ALM models work and where they break. It holds a forthcoming book and a browser-based modeling lab, for educational use only.
01About
Chih Chen
ALM modeling practitioner and author
LinkedIn profileModels are tools, not oracles. They can be useful without being precise or accurate all the time.
Built on one premise.
I start from a single premise: models are tools, not oracles. They can be useful without being precise or accurate all the time, and knowing the difference between a model that is useful and one that is merely elaborate is the central discipline of responsible ALM practice.
This site exists to help fill a gap in how ALM modeling knowledge is shared. The textbook treatments are either too theoretical for practitioners or too product-specific to be portable. The practitioner who built something useful rarely has time to explain it at length, and the explanation is usually compressed into a conference slide. I want to slow that down: to take the behavioral models that actually drive bank balance sheet risk, work through the mechanics honestly, and explain them in a way that transfers across institutions, regulators, and rate environments.
The work here is a forthcoming book with Palgrave Macmillan and a browser-based ALM Model Lab that makes the mechanics visible without a vendor black box. This site sells no advice, training, or consulting. The thread across the work is the same: intellectual honesty, fit-for-purpose thinking, and the practitioner's obligation to know what a model cannot do.
02The Book
Practical ALM
Behavioral Modeling
How Deposit Behavior, Interest Rate Risk, and Liquidity Shape Bank Balance Sheets
Under contract with Palgrave Macmillan, with the manuscript due in January 2027. The book teaches the principles of ALM modeling and how behavioral models connect to the measurements they feed: gap, funds transfer pricing, replicating portfolios, EVE, NII, and survival horizon.
The organizing thesis is George Box: all models are wrong, but some are useful. Every chapter approaches its model class from a risk-aware perspective, pairing the conceptual framework with hands-on mechanics. A single running example, a digital bank named AI First Bank, carries the reader from first principles through model governance. The recurring anchor is the 2023 bank failures, where deposit behavior and interest rate risk converged in a way that made transparent, fit-for-purpose models matter more than elegant ones.
- Publisher
- Palgrave Macmillan, under contract
- Manuscript
- Due January 2027
- Running example
- AI First Bank, from first principles to model governance
- Written for
- ALM analysts, treasury, and risk teams
Chih Chen
Practical ALM Behavioral Modeling
How Deposit Behavior, Interest Rate Risk, and Liquidity Shape Bank Balance Sheets
palgrave
macmillan
03Interactive
ALM Model Lab
A browser-based modeling lab. It bootstraps a US Treasury par curve, overlays SABR on an illustrative volatility surface, calibrates Hull-White and BGM/LMM rate models to that surface, runs Monte Carlo simulation, and drives deposit, CD, and mortgage behavioral models through the ALM analytics that connect rates to the balance sheet. No install, no vendor black box; the assumptions are explicit and the mechanics are visible.
Rate models
Bootstrap the US Treasury curve. Overlay SABR on an illustrative volatility surface; calibrate Hull-White 1F and BGM/LMM to illustrative cap and swaption style surfaces. Simulate forward paths with Monte Carlo.
Behavioral models
A behavioral suite: competing-risks mortgage prepayment and default, demand-deposit and money-market decay, and CD early redemption. The deposit parameters are hand-set, and the mechanics stay visible.
ALM analytics
Repricing gap, liquidity gap, funds transfer pricing, stochastic replicating-portfolio optimization, and the Sensitivity-Equivalent Gap that bridges behavior to risk measures.
Instruments
Fixed and floating loans, mortgages, demand and money-market deposit books, a CD book, and the cash-flow engine they share across every analytic.
→On the roadmap
AI First Bank mini-ALM engine
The book's running balance sheet, modeled end to end inside the Lab.
Open the Lab and run a model.
Calibrate to the bundled quarter-end market snapshot, simulate a rate path, and watch a deposit book decay against it. Built as the book's companion playground.
04Get in touch
Find me on LinkedIn.
Questions about the book or the ALM Model Lab are welcome there.
LinkedIn profile